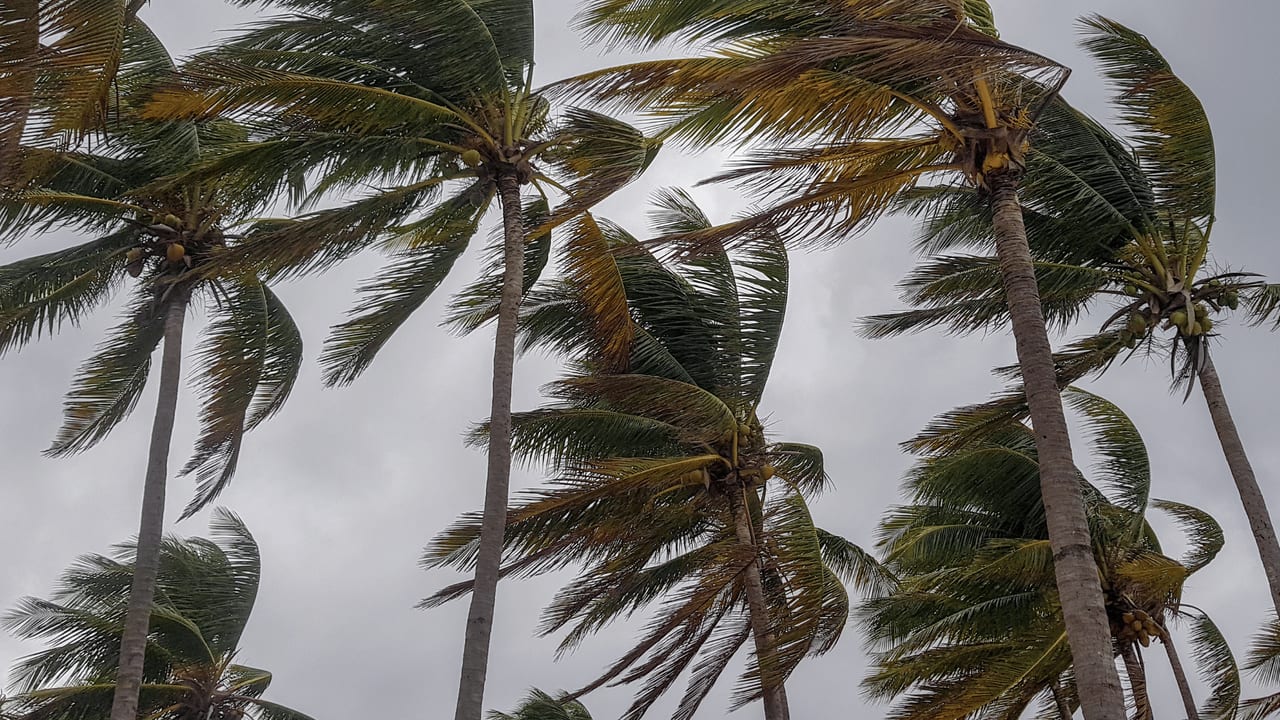
Every fall, we watch closely as hurricanes develop, grow, and change course. The Weather Channel updates us on the latest models, keeping us informed about the storm’s strength and trajectory. Interestingly, there’s a lot that the hurricane world can teach us about retirement planning. Let’s dive into a few similarities.
1) The Eyewall Replacement Cycle: Shedding the Old to Make Room for the New
The most intense winds of a hurricane are found near the center, where the eyewall forms. As the storm matures, the eyewall can weaken, only to be replaced by stronger winds from the outer parts of the storm. This process allows the storm to intensify, shedding “dead weight” and becoming more powerful in the process.
Similarly, as you near retirement, you may need to shed some of the investments that helped you accumulate wealth. Stocks with high growth potential might no longer be the best option to provide the income you’ll need. At this stage, your portfolio needs to evolve. Shift from growth-focused assets to those that prioritize stability and income generation to ensure a more secure financial future.
2) Power Outages: Prepare for Your Own “Retirement Blackout”
One of the most immediate concerns when a hurricane approaches is the possibility of a power outage. You prepare by stocking up on essentials like flashlights, batteries, and non-perishable foods. It’s crucial to have a contingency plan in place to ride out the storm.
As you approach retirement, you face a similar challenge: the loss of your regular paycheck. Have you prepared to replace that income? You’ll need a solid plan for drawing income from your investments. That includes adjusting for inflation, preparing for healthcare costs, and putting an efficient tax plan in place to maximize your assets.
3) Computer Models and Meteorologists: Experience Over Software Alone
In the world of hurricanes, computer models are invaluable tools for predicting the storm’s behavior. But even with the best models, meteorologists use their experience and expertise to interpret data, making them indispensable in storm forecasting.
Retirement planning is no different. While sophisticated software can crunch the numbers, it’s the experience and insight of a financial advisor that can make the biggest difference. A good advisor doesn’t just plug in figures. He or she listens to your goals and personal situation, then applies knowledge and creative strategies to build a plan tailored just for you.